Newsletter Subscribe
Enter your email address below and subscribe to our newsletter
[forminator_form id="25163"]

All voices matter

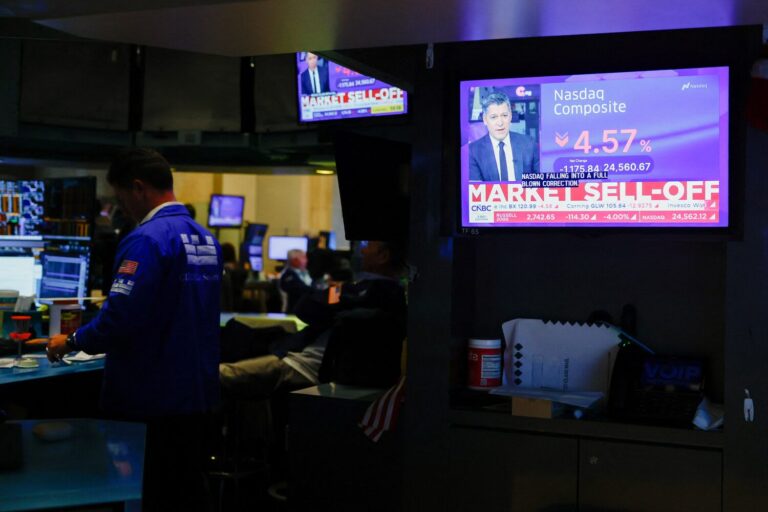
irishsun+1irishsun+1ekathimeriniGovernment borrowing costs across Europe have climbed to or near multi-decade highs as a global bond sell-off, persistent inflation concerns and mounting fiscal pressures reshape the continent's sovereign debt landscape. The broad-based rise in yields has spread beyond traditionally indebted nations to encompass even the bloc's most creditworthy borrowers, raising questions about the sustainability of Europe's fiscal trajectory.
Germany's 10-year Bund yield has risen to around 3.38 percent, its highest level since April 2011, while France's benchmark 10-year yield briefly exceeded 4.20 percent, a peak not seen since October 2008. Italy's 10-year yield climbed to 4.22 percent, and the Netherlands saw its own benchmark reach approximately 3.43 percent, the highest since 2011. Poland's 10-year yield pushed back above 6 percent.irishsun+1
In one of the more striking developments, France now pays more to borrow over 10 years than both Italy and Greece — a reversal that would have been unthinkable during the eurozone debt crisis a decade ago. Greece's 10-year yield has stabilized near 3.93 percent, well below France's, thanks to disciplined debt management, high cash reserves and minimal remaining borrowing needs for the year, according to Ekathimerini. The French-German spread has widened to around 80 basis points, reflecting deepening doubts over Paris's ability to contain its deficits.ekathimerini+1
The pressures are not merely cyclical. European governments are borrowing more to fund defense, the energy transition and the costs of aging populations. The European Central Bank projects the eurozone government deficit will rise from 2.9 percent of GDP in 2025 to peak at 3.7 percent by 2027, with debt approaching 90 percent of GDP by 2028. The Bank of France has warned that failure to reduce the deficit to 5 percent of GDP or below could trigger further rating downgrades.think.ing+2
Renewed increases in oil prices have compounded these domestic challenges, fueling fears of sticky inflation and rates staying higher for longer. Kiran Ganesh, managing director at UBS Global Wealth Management, noted that higher energy prices were adding to upward pressure on yields already driven by fiscal concerns.irishsun+1
ING estimates that a 50-basis-point increase in bond yields could have a slightly greater economic impact than an equivalent ECB rate hike, meaning financial markets are already delivering substantial monetary tightening. Carsten Brzeski, global head of macro at ING Research, warned that the ECB must guard against excessive tightening of financing conditions, particularly if borrowing costs diverge sharply among member states.irishsun+1
The traditional risk hierarchy among European sovereigns is also shifting. As Massimo Spagnol of Generali Assicurazioni Generali S.p.A. Asset Management observed, stronger growth and more stable debt management in Italy and Spain have prompted investors to focus on actual fiscal fundamentals rather than past perceptions of risk — a reassessment that leaves France, not the old periphery, at the center of the market's concerns.irishsun