Newsletter Subscribe
Enter your email address below and subscribe to our newsletter
[forminator_form id="25163"]

All voices matter
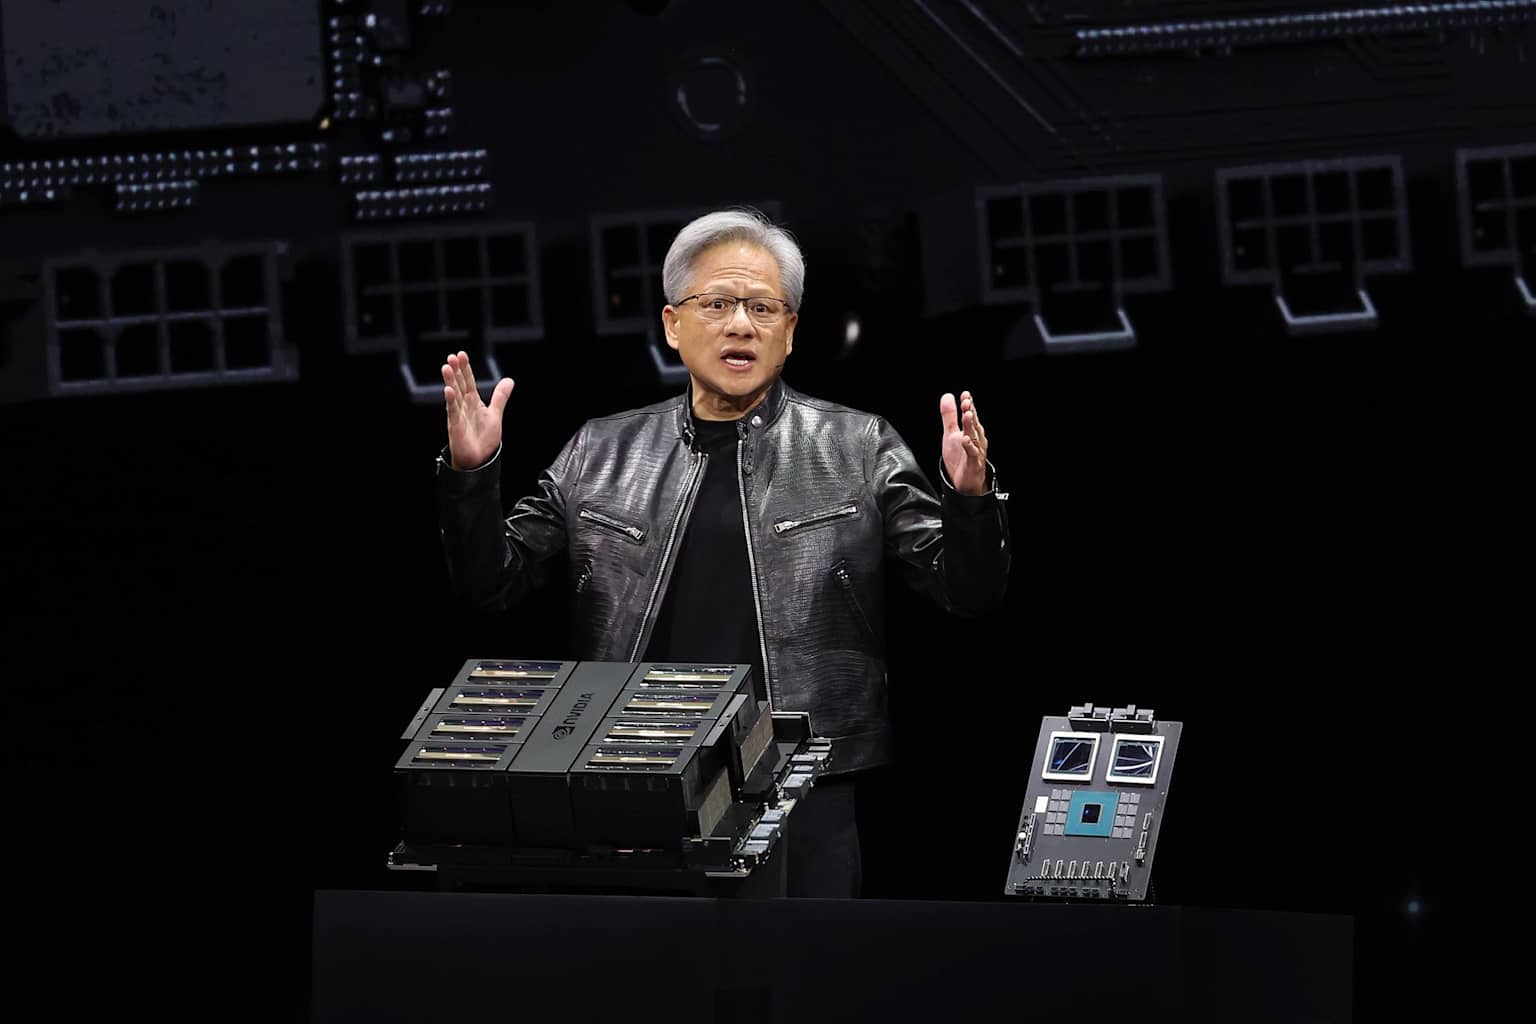
ndtvprofitThe Motley Foolndtvprofit+1Nvidia CEO Jensen Huang declared his company "the world's first and only growth value stock" and called it "incredibly misunderstood," pushing back against a market that has slashed the chipmaker's valuation even as its revenue and profits surge.ndtvprofit+1
Huang made the remarks at Goldman Sachs's Communacopia + Technology Conference on Sept. 10, where he reiterated Nvidia's forecast for 70% revenue growth in its next fiscal year and projected that global AI infrastructure spending would reach $3 trillion to $4 trillion annually by 2030.The Motley Fool+1
Nvidia's forward price-to-earnings ratio has fallen below 17 times expected profit over the next 12 months, according to Bloomberg data — roughly half the multiple the stock commanded in 2025 and the cheapest level in more than a decade. The compression has occurred even as the company's fundamentals have accelerated: revenue and net income are expected to jump 90% and 99%, respectively, in fiscal 2027, which ends in January. Data-center sales grew 117% in the most recent quarter.ad-hoc-news+1
The stock was on track for a six-day winning streak on Tuesday, trading near its 52-week high, yet the valuation discount persists. "The stock has de-rated pretty significantly, which suggests a healthy dose of skepticism that the company's current earnings power is sustainable," said Eli Horton, senior portfolio manager at TCW.ndtvprofit
The valuation gap is especially stark against Apple , which first touched a $5 trillion market capitalization in late July, becoming only the second publicly traded company to reach that milestone after Nvidia itself hit it in October 2025. Investors have favored Apple's predictable cash flows and capital discipline over Nvidia's exposure to the capital-intensive AI buildout.tipranks+2
Nvidia also faces questions about margin erosion. Gross margins are projected to shrink from 75% in the second quarter to below 72% in the fourth quarter as memory chip costs rise. David Russell, global head of market strategy at TradeStation, warned that competition will intensify as major customers like Meta Platforms and Alphabet develop chips in-house. "Companies want to reduce their reliance on Nvidia, so it is very conceivable its market position will weaken over time," he said.ndtvprofit
Despite the skepticism priced into shares, Wall Street analysts maintain a consensus Buy rating on Nvidia with an average price target around $324, implying more than 40% upside from recent levels. TCW's Horton said the current multiple looks compelling. "If the question is whether the multiple will work in your favor by re-rating higher, or work against you, I'd definitely take the former," he said. "This seems like a very favorable multiple to have as an entry point."ad-hoc-news+2